| |
 |
Wednesday, November 4, 2026 |
|
|
Mortgage Market Update
Does your loan term match your life?
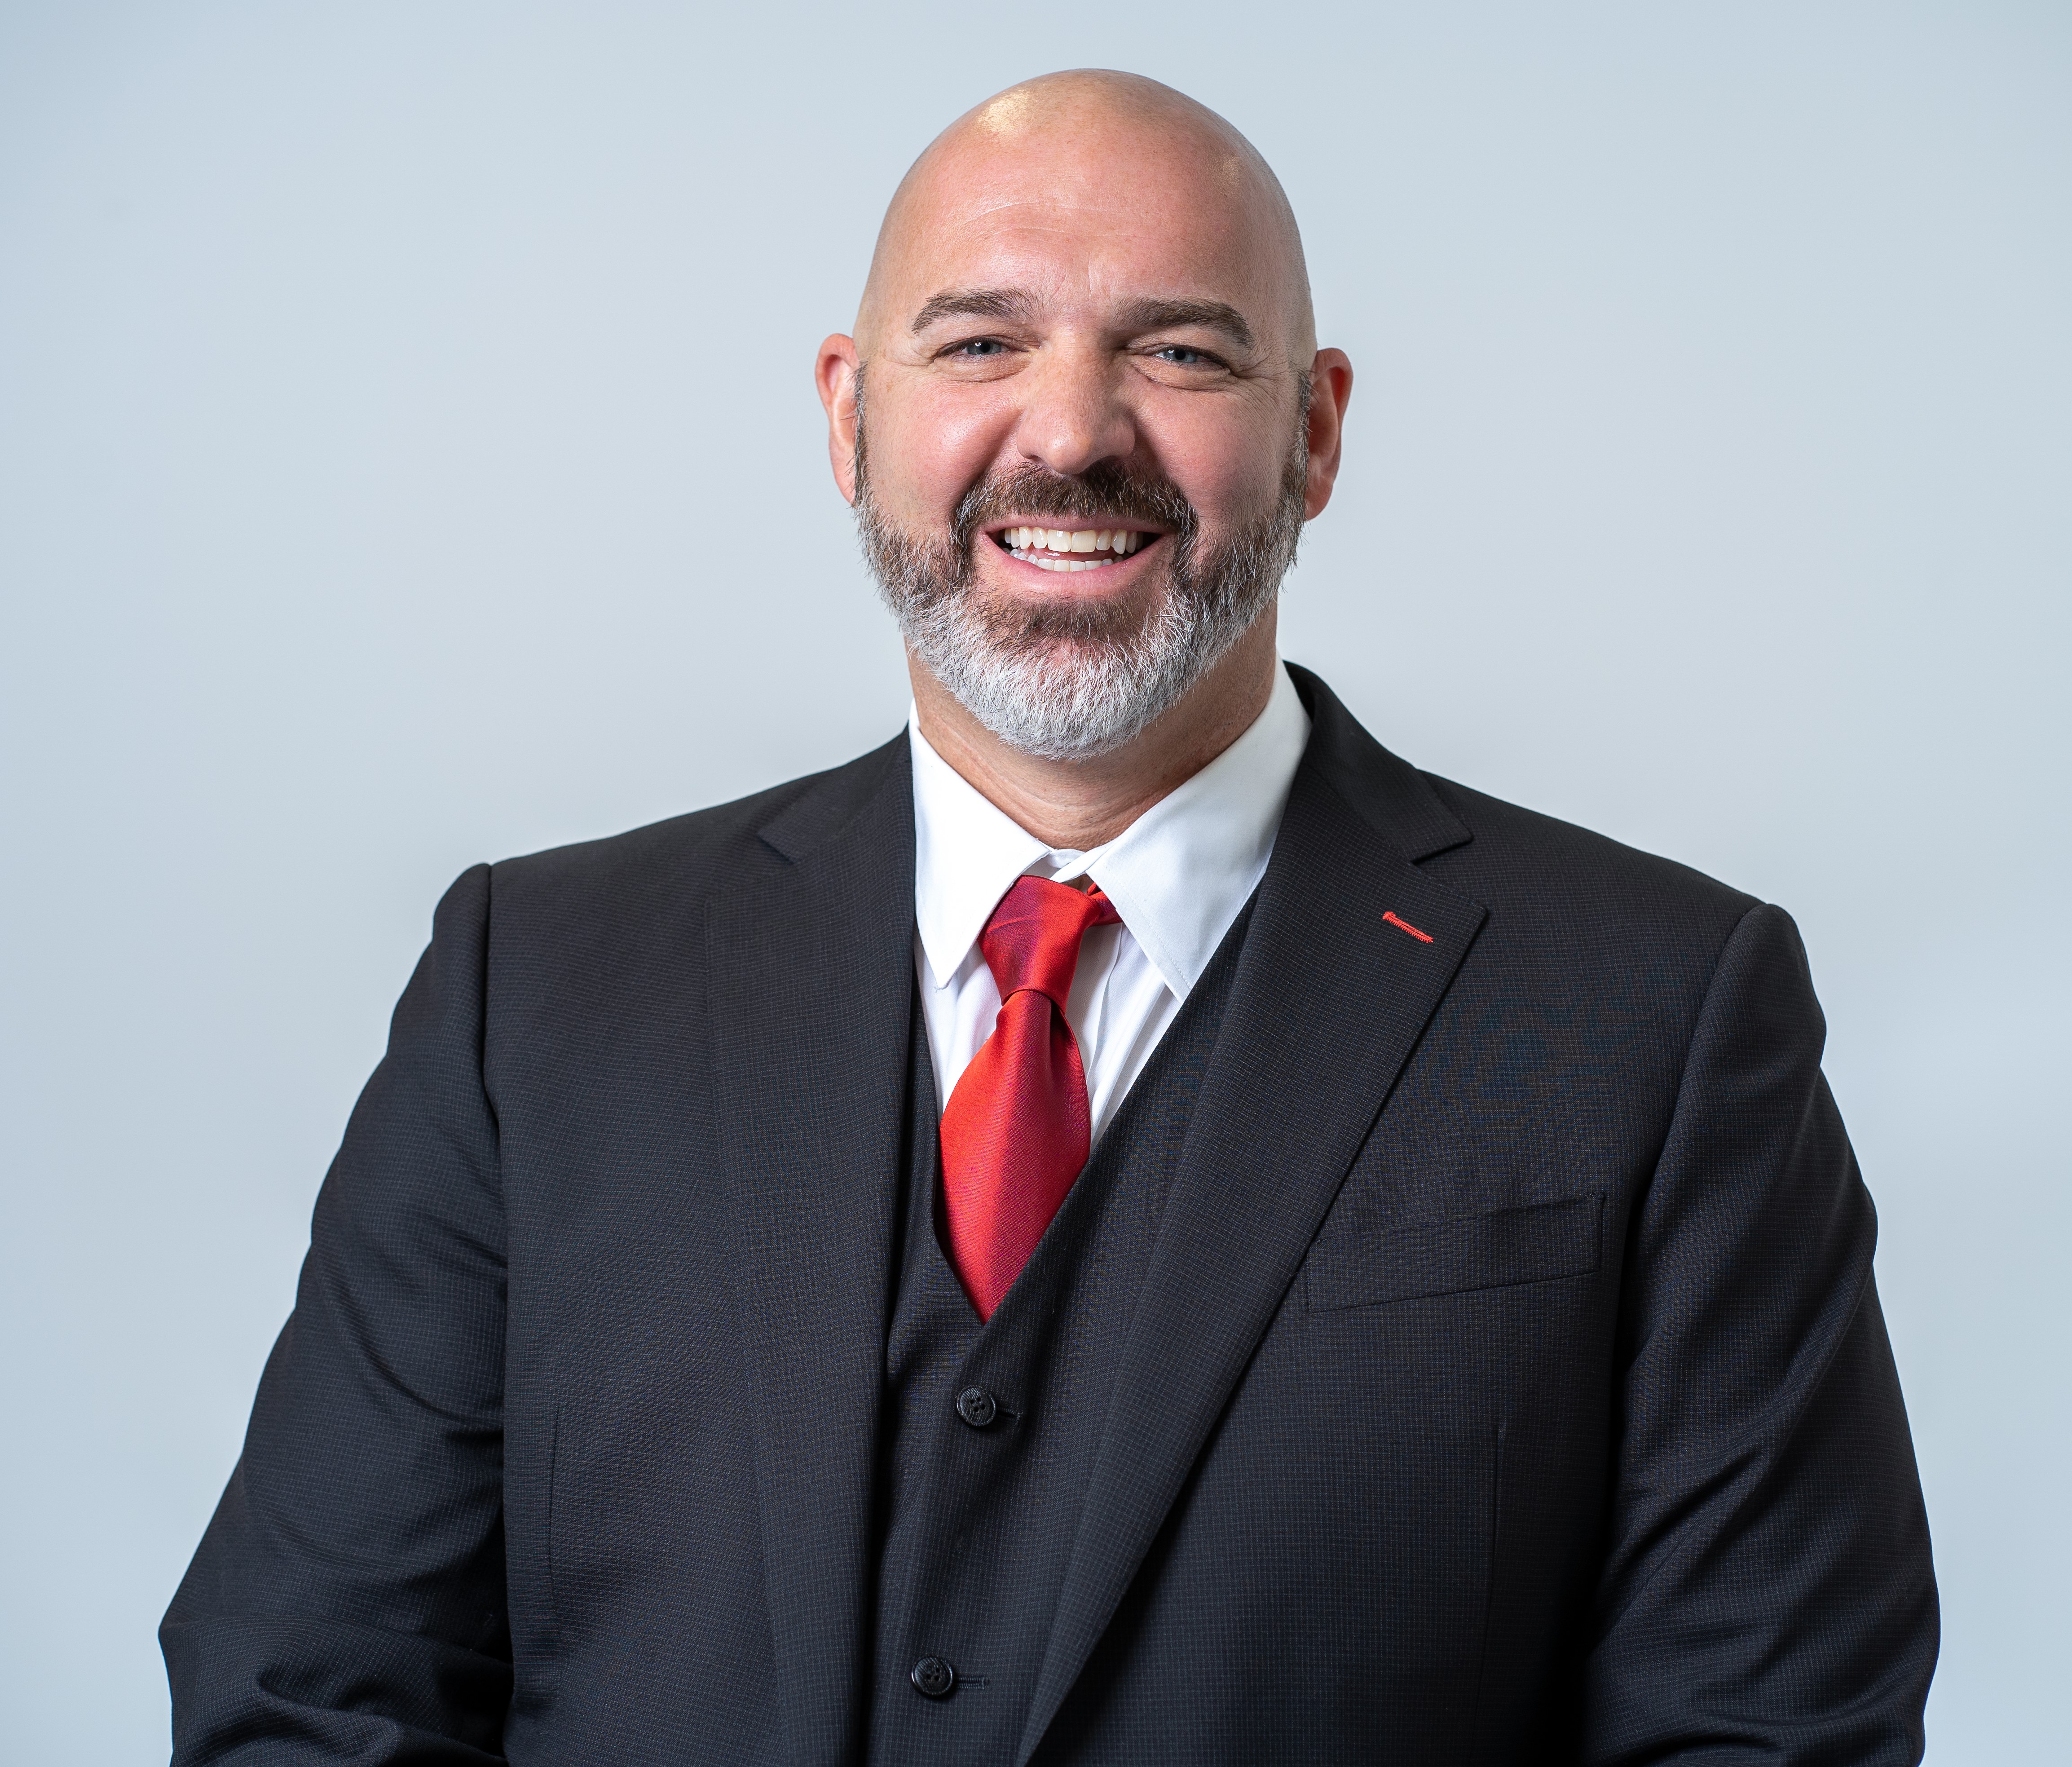
Hi there. This week I want to walk you through one of the biggest decisions in a mortgage—and one that often gets overlooked.
|
|
|
|
National Mortgage Rates · November 5, 2026
|
Conventional 30-Year
7.18%
|
|
| |
|
 |
|
Source: Optimal Blue daily mortgage indices via FRED · 30-yr: Freddie Mac weekly survey
Rates shown are national mortgage index rates and are provided for informational purposes only. Actual rates vary based on credit profile, loan amount, and market conditions. Please contact us for a personalized rate quote.
|
| | |
|
Loan Terms
Why your loan length matters more than you think
When you're shopping for a mortgage, the interest rate grabs all the attention—but the term you choose (typically 15, 20, or 30 years) shapes your finances just as much. A shorter term means higher monthly payments but you'll own your home sooner and pay far less interest over time. A longer term spreads payments out, which can free up cash for other goals, but you're committed longer. There's no universal right answer; it depends on your income stability, other debts, and what matters most to you right now. The good news is we can run the numbers on different scenarios so you see exactly what each path looks like. Understanding this choice upfront keeps you from regret later.
|
|
Tip of the Week
Refinancing resets your amortization clock. If you're 10 years into a 30-year loan, consider a shorter term to avoid paying more total interest.
|
|
Tips for Homeowners
Co-Signing a Mortgage: What You're Really Agreeing To
|
|
1.
|
Co-signing makes you equally responsible for the debt. If the primary borrower misses payments, your credit score takes the same hit and the lender can pursue you for the full balance.
|
|
2.
|
The co-signed mortgage debt appears on your credit report and counts toward your DTI. This can limit your ability to qualify for your own financing until the loan is paid off or refinanced out of your name.
|
|
3.
|
There's no automatic way to remove yourself as a co-signer — the primary borrower must refinance the loan in their name alone. Get this understanding in writing before you sign.
|
|
|
|
Have questions about how any of this affects your mortgage or home purchase? We're here to help — reach out to the Joseph Kelley team any time and we'll walk you through your options.
|
|
3900 Lennane Dr Ste 200, Sacramento, CA 95834
916-612-4294
NMLS# 1705850 · Company NMLS# 02052578
"Joe the Mortgage Giant" · Unsubscribe
|
|